How personal loan interest works in South Africa — and what you really pay
By TODO Author · Updated
Some links on this page are from partners, and we may earn a commission. It does not affect what we write. How we make money
When you take a personal loan, you pay back more than you borrowed. The difference is made up of interest, a once-off initiation fee and a monthly service fee, and often credit life insurance. The interest rate gets the most attention, but the fees and the length of the loan can change the total cost just as much.
This guide explains each part of the cost, shows a worked example and gives you a short checklist for comparing offers.
The three costs on every personal loan
| Cost | When you pay it | What it depends on |
|---|---|---|
| Interest | Every month, on the outstanding balance | Your rate and how much you still owe |
| Initiation fee | Once, usually added to the loan | The loan amount |
| Monthly service fee | Every month, for the whole term | Fixed per month |
Because the initiation fee is usually added to the amount you borrow, you also pay interest on it.
Why the loan term matters so much
A longer term lowers your monthly instalment, which makes a loan feel more affordable. But you pay interest and the service fee for more months, so the total you repay goes up.
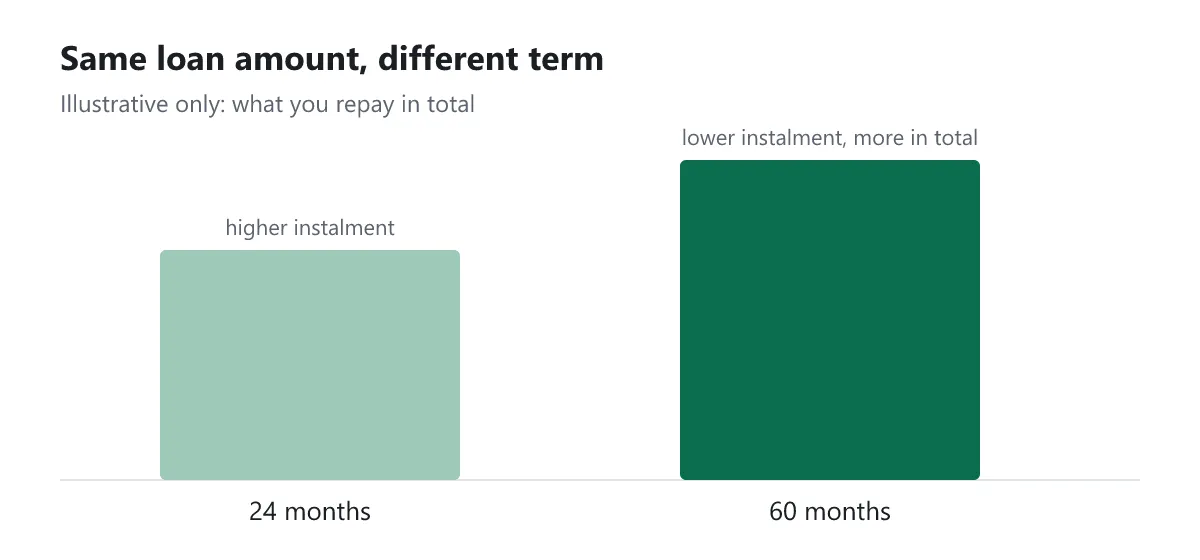
Illustrative example (round numbers, not a real offer): borrowing R20 000 at the same rate over 24 months and over 60 months. The 60-month loan has a much smaller instalment, but you pay the monthly service fee 36 more times and interest for three extra years. In this kind of comparison the longer loan often costs several thousand rand more in total.
How to read a pre-agreement quote
Before you sign, the lender must give you a quote that shows the full cost of credit. Look for these lines:
- Principal debt — the amount you borrow, plus any fees added to it.
- Interest rate — and whether it is fixed or linked to the repo rate.
- Monthly instalment — what leaves your account each month.
- Total amount repayable — the single most useful number for comparing offers.
If two offers have the same loan amount and term, the one with the lower total amount repayable is cheaper, whatever the headline rate says.
Comparing offers without hurting your credit score
Each full application can appear as an enquiry on your credit report. Several in a short time can make lenders more cautious. To compare safely:
- ask for an indicative rate based on a soft check first;
- compare total amount repayable for the same amount and term;
- apply in full only to the offer you plan to accept.
Some lenders let you check your rate online in a few minutes before a full application.
When a personal loan is not the right tool
A personal loan works best for a planned, one-off expense you can repay comfortably. If you are borrowing to pay other debts every month, or you already miss payments, a new loan can make things worse. In that case it is worth reading about when debt consolidation makes sense or speaking to a registered debt counsellor before you borrow more.
Quick checklist before you sign
- The total amount repayable fits your budget for the whole term.
- You know whether the rate is fixed or variable.
- You understand every fee on the quote.
- The lender is a registered credit provider — check the NCR registration number.
Frequently asked questions
Is a lower interest rate always the cheaper loan?
Not always. A loan with a lower rate but a longer term or higher fees can cost more in total. Compare the total amount repayable from the pre-agreement quote, not just the rate.
Can a lender change my interest rate after I sign?
It depends on whether your rate is fixed or linked to the repo rate. Your credit agreement must say which one applies. If it is linked, your instalment can go up or down when the repo rate changes.
Do I have to accept the loan after I get a quote?
No. A pre-agreement quote lets you compare offers before you commit. Take the time to read it and ask the lender to explain any fee you do not understand.
Will checking my rate affect my credit score?
Many lenders run a soft check for an indicative rate, which does not affect your score. A full application usually means a hard enquiry. Ask the lender which one they do before you apply.